Pages

Tuesday, October 23

HOW TO PLACE SHOWER CONTROLS


With some careful planning, your next shower can be a complete joy to use. No blast of cold water when you turn it on, a controlled amount of water falling from each fixture, water that doesn't spray out the shower door and a handheld cord that doesn't wrap around fixtures. Here are some tips on planning the perfect shower experience through the placement of your fixtures.
Many factors influence where to put shower controls. Pipes, heating ducts, exterior insulation, electrical wires and other bits of your home's inner workings hide behind your bathroom walls. Sometimes the structure of your home gets in the way of the perfect control placement. But with care a professional can install a system that works for you.

Tip: Arrange controls for multiple showerheads in an order that would make sense to a guest. You can see multiple showerheads, a steam head and body jets in this shower. Since the rain head is the highest fixture, I'd give its control valve the highest placement. You can have a professional install things any way you like — there's no set rule — but try to create a sensible system from the perspective of someone who has never used your shower before.
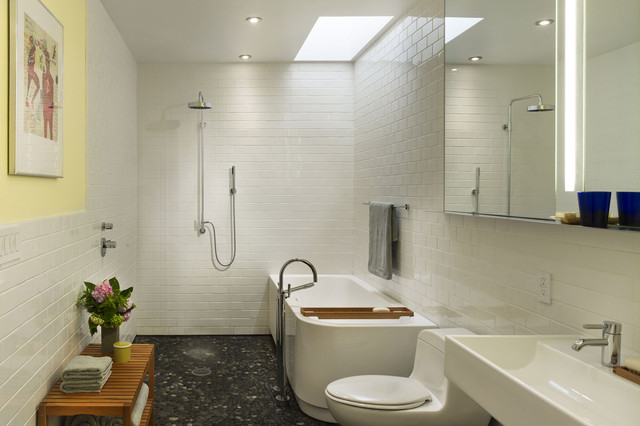
There's no need to worry about splashing here, because this entire bathroom is a wet room. Having the shower's controls at the opening of the shower makes heating things up easy and keeps the homeowners from getting wet in the process.

Tip: When designing a barrier-free bathroom like this, extra care and attention need to be taken where the tub waste and water supply penetrate the floor. Make sure that the floor is angled toward the drain and waterproofed with sheet membranes and waterproofing products, like Schluter's Kerdi Fix or Noble Company's Noble Sealant 150 (regular or low-VOC version).
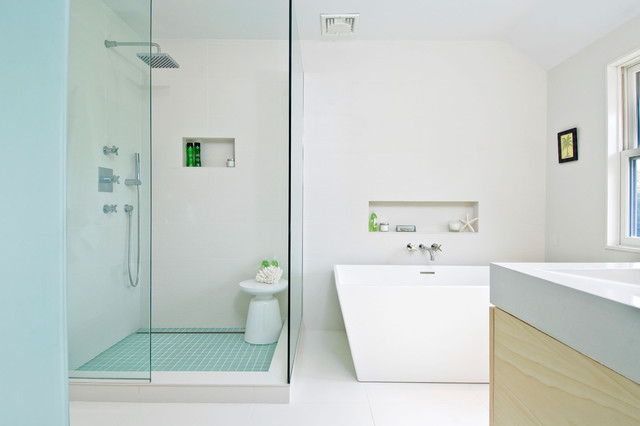
For a handheld shower control, consider the natural arch of the cord. I've found the cords want to curve at roughly 8 inches (20 centimeters). Notice the perfect placement of the shower's handheld cord in this photo. It lines up with the temperature control in middle, and the hose connects to the wall right in line with the lower control valve.

Tip: Have your tile layout ready if you want the hose's connection to fall in the center of a tile or on a grout joint. Siting the connection on a grout joint is easier for the tile installer, but most times it looks best to have it entirely on a full tile.
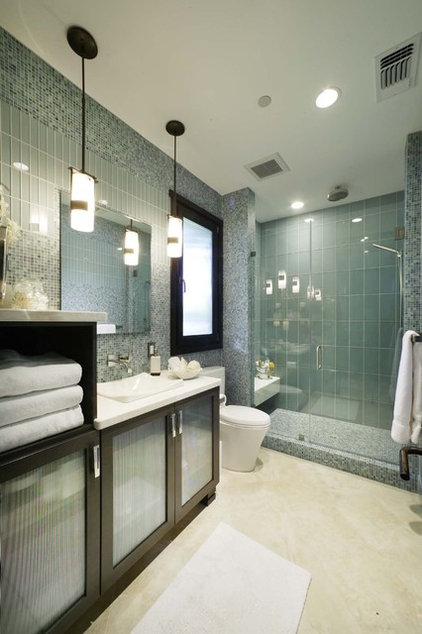
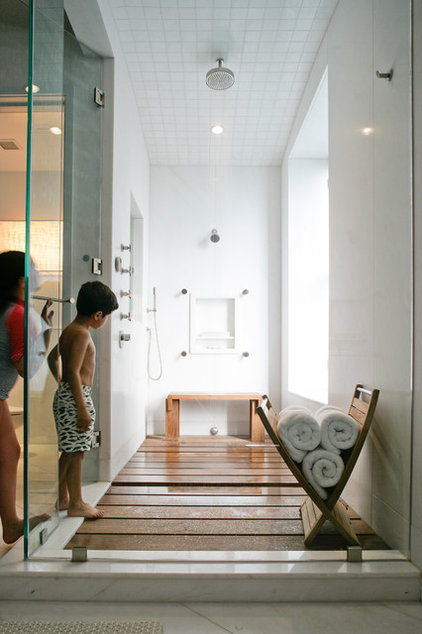
The entry tends to be the most convenient location for the control valves. Placing a handheld shower nozzle closer to the bench makes shaving easier.

Tip: If you cannot install the handheld to be accessible from the bench, consider a low shower niche on the same wall for storage or a place to rest a leg while shaving.
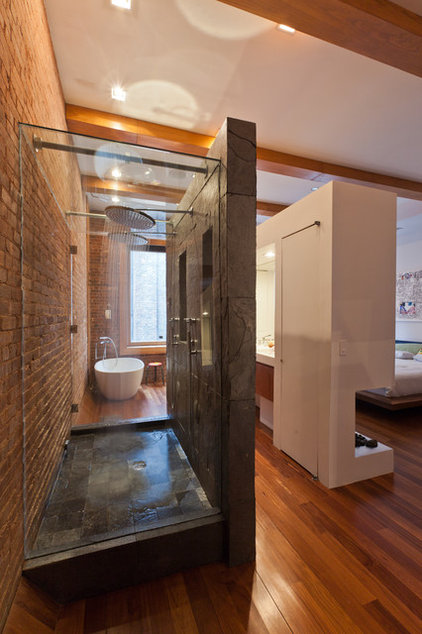
I love this shower and can only imagine how tricky it was to build and waterproof. When you have only one wall to place plumbing on, make sure that the wall is framed or built with the plumbing layout in mind.

Tip: Decide on grout spacing in advance — often this just means coming up with a simple sketch for your plumber. If you have no opinion, you'll most likely get what the plumber thinks looks best, which might not fit with your views.
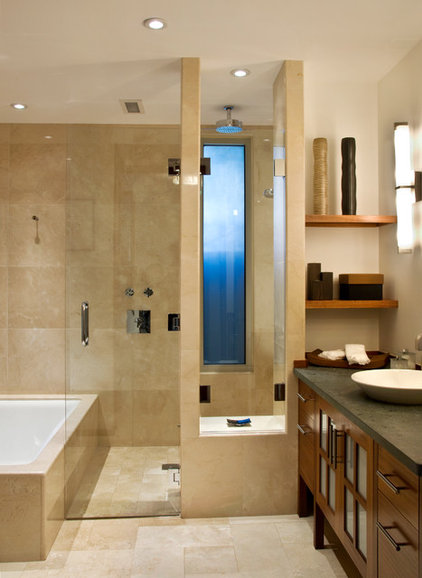
When building a shower with a window, avoid wooden windows and make sure the shower's waterproofing system ties into the window's frame. Remember, windows move! Allow room for expansion and contraction when you're tiling to take moisture and thermal changes into account.

Tip: In this shower, the door shields the user from that first cold start-up spray. When you select your final shower fixture locations, remember that shower doors open both ways. By adding a separate side panel that the door hinges off of, it can open further into the shower without hitting the shower's fixtures.
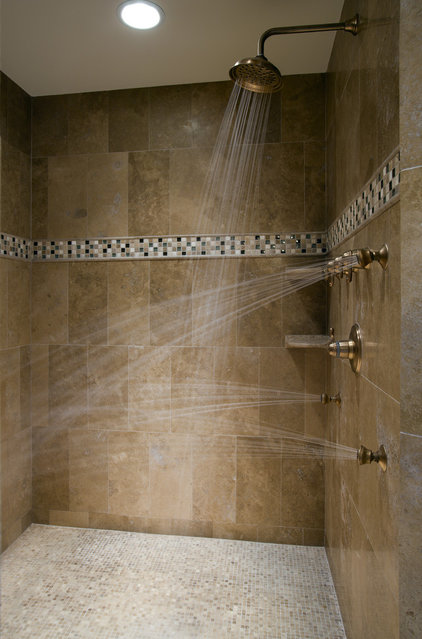
Body jets should never face the shower entry or door. When placing jets, consider how the spray will bounce off bodies and where it will land.

Tip: Jets should be sized to the user's body and installed to hit shoulders and other areas needing a massage. Consider installing them from both sides for a full-body soak!


www.teambluesky.ca

Monday, October 22

Will you fight the latest property tax assessments


What's your property worth? Well, according to the Municipal Property Assessment Corp., likely a bit more than you think.
Ontario property owners can expect to start seeing MPAC assessment notices in the mail any day now, as 2013 marks the beginning of another four-year property assessment cycle.
Properties across the province will be assessed based on what they were worth at the beginning of 2012.
If your home’s value has increased since the last assessment in 2008, that jump will be phased in equally over four years. If it's dropped in value, the change will be recognized immediately, however.
You can check your assessment here, at www.aboutmyproperty.ca. and compare the value of your  property to others in their neighbourhood and community.
Don't like what you see? Well, let MPAC know.

www.teambluesky.ca

6 THINGS YOU SHOULD AVOID BEFORE BUYING A HOME


Buying a home is not an impulse buy. In most cases you will have a few months notice before you actually go through with the sale. Planning ahead is crucial particularly if you don't have extensive financial resources. Since mortgage lenders will be sizing up your finances carefully, don't give them any reason to reject your application.
You never know what effect today’s actions will have on your mortgage application in three or even six months. Even something as simple as transferring money from your savings to your chequing account can negatively impact the mortgage process. So here are some suggestions on things you should avoid before buying a home:

1. Do not make any major purchases
Don't invest in any major purchases. Cars, weddings, jewellery, furniture and electronics can all wait until you're settled in your new home. When you make a major purchase, you limit the amount of money available for your down payment, and decrease the amount of liquid capital in your name.

If you do have to make a major purchase before buying a home, you might want to put it on a low-interest credit card until after your mortgage application is approved. Sometimes you can't control what life throws your way, but think carefully about your options before making a decision.

2. Don’t move money around
When a lender reviews your loan application for approval, one of the things they are concerned about is the source of funds for your down payment and closing costs. To do so, they will request statements from all of your accounts that contain liquid assets.
Moving your money around, even if you are consolidating your funds to make it "easier," could make it more difficult for the lender to properly document and measure your finances. So leave your money where it is until after closing.

3. Do not make large investments
It is also not recommended to make investments just before buying a home; again, you're decreasing the liquidity of your assets. If you've come across a new stock in which you'd like to invest or if it's a great time to buy bonds, wait until after you've settled the finances on your home.

Furthermore, you'll have to disclose all of your finances before buying a new home, which means accounting for every withdrawal and deposit in all of your accounts. This can get quite tedious, especially if you're trying to dig up cancelled cheques for the new home theatre or HDTV you just had to have three months ago.

4. Do not change your bank 
Changing banks is always a hectic ordeal, so don't do it before buying a home. You'll have to provide information about previous accounts that are now closed, and therefore inaccessible. And if you diversify your money too much in money market accounts, savings accounts, chequing accounts and other places, you'll have a harder time with the disclosure process.

If you're frustrated with your bank and want to change, tough it out a little longer and switch after your mortgage is approved and you've set up shop in your new home. This will save you hours of headaches and frustration.

5. Do not apply for a new credit card or line of credit
Even though the inquiry won’t hurt your credit too badly if you already have a good credit score, the additional credit card will cause the lender to question your financial stability for buying a home.

6. Do not change your job unless absolutely necessary
Try not to change jobs. Your employment is a key factor in the mortgage approval process, and if you can't show steady employment, you might be denied. Of course, you can't help matters if you've just been laid off or an opportunity presents itself that you can't pass up.

This could become more difficult if you become self employed. In most cases, lenders want to see at least two years of self-employment before they will approve you for a loan. So if you can, wait until after buying a home to become self-employed. For part-time workers, changing jobs creates unpredictability in the number of hours you will work so the lender cannot determine your gross income to qualify you for a loan.

If you're going to change jobs before buying a home, wait another six months before going ahead with the real estate transaction. This gives you an opportunity to establish employment and to show a steady income from a single employer. This looks much better on a loan application than a long list of recent employers.
As mentioned above, there will be times when you can't avoid all of these things before buying a home, but know that it's in your best interests to wait until the dust settles. The goal should be to move into your new house with as few obstacles as possible.


www.teambluesky.ca
Friday, October 19

EVICTION TIP SHEET


Late payments, bouncing checks – these are just a couple of the warning signs seasoned landlords look for. But while evicting a troublesome tenant may seem the easy solution, doing so isn’t quite as simple.  We asked Harry Fine, a paralegal specializing in landlord and tenant law, to give investors a list of the top four tips for first-time landlords looking to go the eviction route.
 
Prepare for a battle 
As Fine points out, investors keen to evict a tenant should first be aware it’s no straightforward process. “The single biggest mistake landlords make is not recognizing evicting a tenant is a highly regulated business,” he says. “They had better be familiar with the process, or retain someone who is, before they start the eviction.”
Separate fact from fiction 
There are several urban legends haunting the industry and lingering on the Internet about what a tenant is entitled to, but Fine advises to do your due diligence and realize what your entitlements are under the LTB. “On rent applications, the Landlord Tenant Board under the act does not evict and get you your money; it only does one or the other,” he says. “The way the process works under the law is that if the tenant pays, the tenant stays. So right up to the moment the sheriff comes to the door, the tenant has a right to be there – if they pay.”
Research your options 
A Google search for “When can I evict my tenant?” returned 814,000 results. Needless to say, compiling the answers yourself will be a cumbersome task. Instead, Fine suggests sticking to the free resources provided by your local LTB such as its website and free call centre, as well as soliciting legal counsel from a professional who specializes in landlord and tenant law, is licensed by the Law Society of Upper Canada and affiliated with their local LTB.
Don’t hesitate 
Fine advises to nip an issue in the bud quickly, rather than let it drag on. “Don't write 10 letters saying the same thing.  It's like the brakes on your car; when they start to squeak, they never get better without some action,” he says. “Give one warning, one letter, and then do the appropriate termination notice, likely an N5, which is remedial...if the tenant corrects the behaviour, the problem goes away.  By waiting, you are simply making the damage worse, the behaviour more entrenched, and letting other tenants be disturbed by the behaviour, opening yourself up to meritorious claims from other tenants.”

www.teambluesky.ca

Thursday, October 18

RAISING THE RENT


Landlords don’t want to scare away tenants by raising the rent, but here’s a lesson in how and why to do it.  
Income properties are in essence a business, and as such, you are constantly trying to increase income and decrease expenses. One of the easiest ways for landlords to do the former, at no cost and little effort, is to ensure that they hand out their annual Rent Increase Notifications in a timely manner. This will both strengthen your cash flow and in turn increase the market value of your property.
In most cases, the rent for a unit can be increased if at least 12 months have passed since a tenant first moved in, or if at least 12 months have passed since the last rent increase.
Proper Notice
Typically at least 90 days written notice is required. The governing provincial body provides forms to be used for rent increase notifications. In Ontario, the form is an N1 - Notice of Rent Increase. In B.C., the form is an RTB-7 - Notice of Rent Increase. Prudent landlords will have already issued their rent increase notifications for 2013. For those not-so-prudent landlords, if you act now and issue your rent increase notifications anytime before Nov. 1, the rent increase will take effect starting Feb. 1, 2013.
Rent Increase Guideline
The rent increase guideline applies to most private residential rental accommodations with certain exceptions. The guideline varies from province to province so make sure you check with your governing provincial body. In Ontario, the maximum allowable rent increase for 2013 is 2.5% (which also happens to be the maximum allowable under the recently imposed cap in Ontario). In British Columbia, the maximum allowable rent increase for 2013 is 3.8%.
Small Increase = Big Effect
Let's look at increasing the rent of just one unit, which currently rents for $800/month. The allowable rent increase guideline in Ontario was 3.1% for 2012. As such, you could increase the rent of this unit to $824.80/month. (You may be tempted to round it to $820 or $824, but that would be a mistake as every penny counts.) You have now increased the income that this one unit generates by $24.80/month or $297.60 on an annualized basis. It doesn't seem like much until you put the power of the multiple to work. $297.60 in annual income is worth $5,952.00 in market value based on a 5% cap rate. And that is just one unit. How about if you have 6 or 12 units that are due for a rent increase?
Will I Lose My Tenant?
One of the most common reasons that landlords do not issue rent increase notifications is that they fear they will lose good tenants. In all my years of handing out notifications, I've never lost a tenant due to the increase (some have complained but never left). At the same time, if it does become a point of contention, you as the landlord have to explain to them that your operating costs are continually subject to inflation. This includes, property taxes, hydro, water, gas, waste removal, etc... Unfortunately inflation is a part of our lives and unless you as the landlord are issuing Rent Increase Notifications, you alone are absorbing the ever increasing operating costs which eat into your cash flow and thereby reduces the market value of your property.

www.teambluesky.ca

Monday, October 15

WHAT THE CONTRACTOR REALLY MEANS....


Contractors didn't become contractors because they love to communicate. If they did they would have become speechwriters or newscasters (or get a gig writing ideabooks for Houzz). Sometimes what they say seems completely obvious to them, but makes no sense to you. And a contractor might speak euphemistically to dance around difficult topics. These tips should help you translate some of the euphemisms and somewhat curt statements you might hear, so that you get the most out of the client-contractor relationship.
1. Nothing. If he doesn't call you back, he's just not that into you. You don't want to chase a contractor who's too busy to return your call, unless you've given him money.

2. Let's do it my way instead. Odds are, your contractor has more experience doing things a certain way, so he may want to recommend that process. It's usually best to go with it rather than having him try something for the first time on your job.
3. I'll get started late next week. If your general contractor sets a start date, he should be able to keep it. But many times the tradesmen (plumbers, electricians, etc.) juggle several jobs at once and often have to deal with emergencies. You should expect them only to come close to their start and completion estimates.

4. The price is... 
Unless you're changing the scope of work, a contractor won't expect to negotiate a lump sum price quote. If you think the price is too high, get another quote for comparison. While prices vary because of differences in approaching the project or overhead costs, a contractor won't stay in business unless he prices competitively.
5. I'll do my best. There is a good chance a contract will fall short of your expectations. If you hear this, listen to your gut. Are you asking for too much? Have you added work to the scope, but asked for the project to be completed by the same date? Are you expecting a brand new look from a remodel with existing elements?

There are three elements to any project: The level of quality, the price and the time it takes to complete the project. Pick two of these that are most important to you. If you need everything perfect by a certain date, be prepared to pay more. If you have a fixed budget but want a certain look, give the contractor time to be creative and make it work.
6. Sorry, I can't make a recommendation. Most contractors prefer that you work through them. If you ask your general contractor for their plumber's name and number and he gives it to you, thank them. By allowing you to work directly with a subcontractor your contractor takes a risk by giving up control of the situation. He also gives up the ability to mark up the cost of the work the plumber does, which is one of the ways contractors get paid.
7. The design needed some tweaking. Often, this means the plans were unbuildable. Sometimes what's drawn on paper just can't be built. A staircase you'd need to crawl on your knees to use, "existing" spaces that don't exist, a pocket door that would slide through a switch box and the shower valve — I've seen them all.

8. I don't think this is a good fit. If a contractor declines to quote a project it could be for a lot of reasons. Maybe he has concerns about the budget. You and your contractor will be talking a lot, so maybe he just didn't think you clicked. It could also be that he's too busy, and he won't be able to devote enough time to your project to do it right.
9. We are going to need to do some value engineering. You've got caviar dreams on a cheese and cracker budget. Value engineering is when the team thinks creatively about how to rework the project to do the same or similar scope for less, like by changing material selections.

10. Let's walk through and make a punch list. A contractor wants to know everything you need done to be satisfied with the work. Every trip to your job costs your contractor, so make an effort to come up with a complete punch list —a list of to-do items that need to be completed for the project to be considered complete — instead of sending it bit by bit over time.
www.teambluesky.ca

Friday, October 12

"MY TENANT WRECKED THE PLACE! NOW WHAT?"


“I successfully evicted a tenant on September 5, 2012 at 8:40 AM by Sheriff but they destroyed the apartment. They broke the bathroom sink, the toilet, the doors, windows, light switches, put peanut butter everywhere, put ketchup on the ceilings, walls, everything they could break they did break. They even poured dried rice down the sink to clog it and opening the water would cause the rice to expand and make it worse.”
Alice from Waterloo writes about how her daughter was told by her landlord to leave the premises early and then sent a bill for $800 for clean-up costs. The landlord also threatened that if the amount wasn’t paid immediately, the bill would be sent to a collection agency and it would ruin her daughter’s credit rating. Her daughter indicated that there was nothing wrong with the apartment when she left.
These emails raise all kinds of issues as to what to do to protect yourself when a lease comes to an end. Here are some things to consider:
• Landlords will have to prove that damage was done. Landlords and tenants should prepare and sign a form called a rental unit condition statement, which is similar to what you sign before you rent a car. You go through the apartment and make a list of everything; whether there are any damages and confirming that everything is working. Then you should do the same thing at the end of the tenancy, to both agree on any damages that may have been caused by the tenant.
• Landlords should regularly inspect the unit during the lease, to make sure that it is being properly cared for by the tenant. You have to give 24 hours’ notice and can get in during the hours of 8 a.m. to 8 p.m. to do it. If you notice any damage, you can immediately demand that it be fixed, or consider an application to the Board to get the tenant to fix it.
• Landlords should respond to requests by the tenant to fix things that break down in a timely manner.
• Tenants should also take pictures of the unit when they leave as additional proof that they left the place in similar shape to what they got in the first place.
Once the tenant leaves, you will have to go to Small Claims Court to sue for any damages. You can sue for any amount up to $25,000 in Ontario, which usually is enough for most of these types of claims. When deciding whether to bring a claim, ask whether you are going to collect anything if you win. If the tenant has disappeared, it may just be a further waste of money to sue. However, if you know where the tenant is working, it may be worth your while. Consult with a lawyer or paralegal before making these types of decisions.
Landlords cannot threaten to ruin a tenant’s credit over these types of issues. In my experience, the Ontario Ministry of Consumer Services would probably consider this type of claim to be an unliquidated damage, meaning it is just an accusation and has not yet been proven. As such, if the landlord or their agent reports you to the credit bureaus over this, in my opinion, you can report the landlord to the Ministry by calling (416) 326-8800. Do not let someone bully you into paying for any damage that you did not cause.
In my experience, when landlords do more during the lease to be appreciative of their tenants and proactively try to work things out, it will reduce the risk of any damage being done to the unit when the tenant vacates.
Mark Weisleder is a Toronto real estate lawyer.

www.teambluesky.ca